Sponsored Links

Cheap Drones Are Breaking Old Defense Math


Low-cost drones are reshaping U.S. air defense. And securing the small components for them is becoming a major defense priority...
 
Not rendering correctly? View this e-mail as a web page here.

Cheap Drones Are Breaking Old Defense Math

By Joel Litman, chief investment officer, Altimetry


Russia has sent thousands of unmanned, self-destructive drones into Ukraine...

A Shahed-type drone costs about $35,000.

More traditional air-defense weapons cost up to 10 times as much... A Patriot interceptor, for example, has a $3 million-plus price tag.

These munitions can burn through a defense budget and quickly deplete inventories.

That's why Ukraine is turning to low-cost interceptor drones that are roughly $3,000 to $5,000 each. These drones can break through defense lines. And they're easy to restock.

As we discussed last week, the U.S. is working through its own strained inventories of high-end missiles. Replenishing them will take years.

Today, we'll explain how cheaper drones are reshaping U.S. air defense... Securing the small components for this technology is becoming a major defense priority.

A cheaper air-defense shield is already taking shape...

And Japanese drone developer Terra Drone is a big part of that effort.

The company is replacing pilot-centered missile responses with autonomous aircraft that hunt down other drones.

Terra's interceptors combine simple components – like radar, cameras, and AI-powered software – to find and pursue targets. The interceptor then destroys them head-on.

An operator can supervise the mission from a computer instead of manually flying the aircraft.

This type of automation reduces the human and financial burden of defending against mass drone attacks.

Terra entered the defense market in 2026 after spending years working on commercial drones. Its Ukraine operations have given the company a close look at battlefield drone technology... and how quickly it can change.


Recommended Links:

'Days From Now, a Desperate, Multi-TRILLION-Dollar White House Move to Save America Will Shock the Market'

The man who has been paid $100,000 for one month of his financial research is sharing the biggest stock story of 2026... and history says it could 23X your money as it unfolds. Click here to learn more (includes a free recommendation).


Dr. Ron Paul: 'I Warned Congress. Now, I'm Warning You.'

In his farewell address, Dr. Ron Paul warned Congress about the direction America was heading in. Today, he believes that warning is starting to come true. A multibillion-dollar government experiment is now reaching the heart of the American stock market. And you're running out of time to prepare.


Japan's defense-procurement agency (the Acquisition, Technology, and Logistics Agency) has already approved Terra's B1 interceptor for mass production after the company fast-tracked development.

Terra describes the B1 as a lower-cost alternative to traditional interceptor missiles (like the Patriot). Although it doesn't provide a specific price tag, we know that new interceptor drones cost a few thousand dollars apiece.

They would help lower U.S. military defense spending. That, in turn, would allow America to invest in the high-tech parts of drone technology...

The next bottleneck sits inside the drone...

These cheaper military tools only work when manufacturers can reliably source the electronics inside them.

That's where China, and its big production capacity, comes in...

Chinese companies control about 70% of the global consumer drone market. Companies outside of China charge 3 to 5 times more for the same drone technology.

Terra's CEO Toru Tokushige has described the same pricing pressure across batteries, controllers, and motors.

Terra's first Japanese-government interceptor was only about 20% locally sourced. The company wants to raise that share, even though domestic components cost more.

Taiwan offers another major electronics base and a middle ground for price. Of course, China continues to rattle its saber at Taiwan. And any disruption around the island would put its supply lines at risk.

That makes local sourcing the only "safe" option. A military program using a $5,000 interceptor can tolerate an expensive battery, sensor, or control board and still save millions of dollars.

The point is, paying more for these parts today ensures that the weapons are available for future conflicts.

The U.S. is already building that ecosystem... The Department of Defense's Blue UAS program cleared 165 individual components by late 2025. These include flight controllers, radios, cameras, and navigation receivers.

Washington-state radar maker Echodyne has already integrated its compact radars into dozens of counter-drone systems. And it's investing $40 million in a new plant to lift annual production capacity to more than 30,000 radars.

Small suppliers are becoming strategic investments...

The drone boom is changing the nature of defense spending.

Big contractors, like Lockheed Martin (LMT) and Northrop Grumman (NOC), are still assembling the finished systems. But the key suppliers are the smaller players down the supply chain.

Companies with reliable domestic production need to supply the parts that every drone maker suddenly needs, in large amounts.

Rearmament is already forcing governments to expand production, and cheap autonomous systems add another source of demand.

I recently went on camera to explain how military buyers are placing more value on secure sourcing... and how small U.S. component manufacturers are gaining leverage inside our defense programs.

These smaller companies are the real story behind America's munitions crisis. Click here to learn the exact steps you should take to capitalize on this next wave of wealth.

Regards,

Joel Litman
September 28, 2026


Monday Starts With (NASDAQ: PMAX) at the Top of Our Radar — An Approx. 280% September Move, a Funded Balance Sheet, and a Named First Acquisition


Any content you receive is for information purposes only. Always conduct your own research.

*Sponsored

Street Ideas Just Put Powell Max Limited (NASDAQ: PMAX) On The Watchlist This Morning—Monday, September 28, 2026

Don’t Miss Our Next Update—Get Real-Time Alerts Sent Directly To Your Phone. Up To 10X Faster Than Email.

We’re Laser-Focused On (PMAX) This Morning…

September 28, 2026

Dear Reader,

Monday morning is here, and Powell Max Limited (NASDAQ: PMAX) is one of the first names we’re focused on as the market begins to digest just how much has changed.

When a company's corporate structure changes faster than the market's understanding of it, the result is usually a disconnect — a window where the data tells one story and the valuation hasn't caught up yet.

These kinds of windows don't last forever…

But while they're open, they tend to reward careful attention.

That's exactly what's unfolding right now with Powell Max Limited (NASDAQ: PMAX) — and it's why the company that’s topping our watchlist this morning, Monday, September 28, 2026.
Inline Image

On paper, Powell Max (NASDAQ: PMAX) is still classified as a financial communications firm — a Hong Kong-based subsidiary called Jan Financial Press Limited that handles typesetting, regulatory filings, and compliance documentation for companies listed on the Hong Kong exchange.

In practice, the company has quietly restructured itself into a Nasdaq-listed diversified holding company with a funded acquisition strategy spanning solar energy, enterprise AI, entertainment technology, medical manufacturing, and IoT infrastructure…

And the restructuring happened fast.

New leadership.

A $17M capital raise.

A named first acquisition target with $24M in annual revenue.

And a per-share structure so tight — fewer than 1.5M shares in the public float — that even modest demand has already made an approx. 280% move in September alone, from roughly $0.75 to $2.86.

Keep in mind, (NASDAQ: PMAX) has a float less than 1.5M listed as available to the public — with a float that small, the potential exists for big moves if demand begins to shift.

The Roll-Up Playbook — And Why the Timing Matters

The transformation at the corporate level began in January 2026.

Geordan Pursglove was appointed Chairman and CEO.

Anna Skowron stepped into the CFO role.

Four independent directors joined the board — among them Andrew Hancox, founder of Block 8 Ventures and a former COO who helped raise over $250M in debt and equity at Katapult, and Phillip Balatsos, a 25-year financial markets veteran currently with Oscar Gruss & Son.

The same month, the company closed a $17M PIPE with accredited participants at $2.89 per unit — providing the war chest needed to begin executing an acquisition-driven growth strategy.

According to a Zacks Small Cap Research report from April 2026, the stated plan is to acquire more than five companies within 18 months at 3x–6x EBITDA, with a target of exceeding $50M in consolidated revenue and building a recurring/SaaS revenue mix above 40%.

The strategy isn't theoretical…

It's already in motion.

A Revenue-Generating First Acquisition

On March 23, 2026, the company announced a non-binding Letter of Intent to acquire The Boston Solar Company, a vertically integrated EPC solar installer operating in Massachusetts and the broader New England region for 13 years.

The deal is valued at $9M, including the assumption of up to $7M in debt.

What stands out about this target is the quality of the underlying business…

Boston Solar reported 2025 revenue of $24M — up 22% year over year — with adjusted net income of approximately $2M.

The revenue split is 65% residential and 35% commercial, with a client roster that includes Fenway Park, MGM Music Hall, a large federal agency, a luxury hotel chain, and various global manufacturers.

The company is led by President Mike Morlino, a distinguished U.S. Navy SEALs veteran, and its model is fully vertically integrated — handling everything from financing to design to installation with licensed, certified in-house crews.

Following closing, the company expects to provide up to $20M in working capital to support Boston Solar's expansion into five adjacent Northeast states, with planned diversification into battery storage, EV charging, HVAC, and efficiency services.

Chairman and CEO Pursglove described Boston Solar as "a strong platform for long-term growth," citing rising U.S. energy demand fueled by AI, automation, and rapid technological change.

The solar installation space remains highly fragmented — thousands of regional installers nationwide operate without the capital or back-office support to scale — and Boston Solar's vertically integrated model is positioned as the blueprint for replication.

The company has already mapped its own growth trajectory: geographic expansion into five adjacent Northeast states, service diversification into battery storage, EV charging, HVAC, and efficiency services, and an M&A strategy to acquire regional EPCs across New England, California, and Canada.

That expansion plan is significant…

The solar EPC space is ripe for consolidation, and a Nasdaq-listed parent with a funded balance sheet provides exactly the kind of infrastructure a regional installer needs to move beyond its home territory.

The macro data supports that framing.

According to Grand View Research, the U.S. residential solar PV market is expected to reach $17.68B by 2030, expanding at a 14.4% CAGR…

That's the kind of secular tailwind that can carry a well-run regional operator a long way.

The Deeper Pipeline

The research case for (PMAX) extends well beyond a single solar deal.

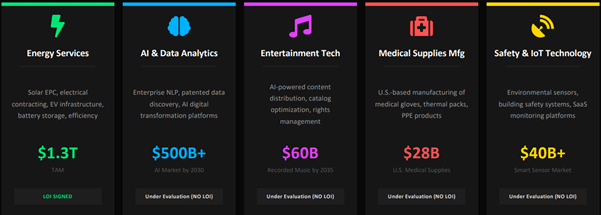
According to the Zacks report, the company is in preliminary discussions across three additional verticals, each with its own defensible IP and recurring revenue characteristics.

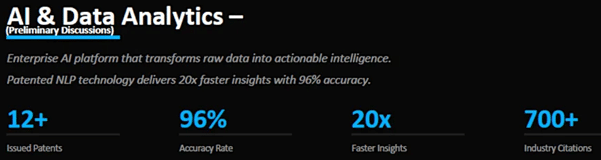
The first is an enterprise AI platform built on patented Natural Language Processing technology — delivering 20x faster insights with 96% accuracy…
Inline Image

The platform holds more than 12 patents, and its technology has been cited by Apple, Microsoft, IBM, Google, and HPE.

It operates under an enterprise SaaS model and could be deployed as shared analytical infrastructure across the broader holding company — a connective layer powering decision-making in every subsidiary.

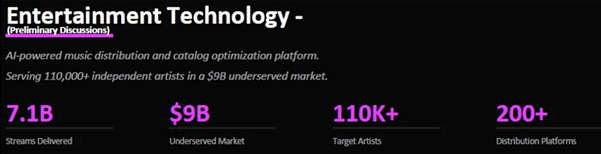
The second is an AI-driven music distribution and catalog optimization platform serving 110,000+ independent artists in a $9B underserved market…
Inline Image

Its offerings include royalty optimization tools — reportedly capable of driving 20%+ uplift — and a catalog bundling strategy that packages 20–50 music catalogs for sale to institutional participants at 8x–10x multiples, generating a 20% commission per transaction while retaining post-sale distribution rights.

The third spans two divisions: a U.S.-based medical supplies manufacturer operating from a 14-acre facility — producing examination gloves, thermal packs, and personal protection equipment — and an environmental and biometric sensing platform with 30,000+ units deployed across 40+ countries…

That IoT division reportedly generates gross margins exceeding 50% and holds more than 20 U.S. and international patents.

Across the full proposed portfolio, the company is targeting 30+ combined patents and a revenue base that blends hardware, software, services, manufacturing, and SaaS — with the kind of diversification that reduces concentration risk while creating cross-portfolio synergies through shared AI tools, centralized compliance, and public-market capital access.
Inline Image

The patented NLP platform is worth particular attention here…

Its potential to serve as operational infrastructure across energy analytics, entertainment catalog valuations, and medical quality control could turn a collection of separate acquisitions into a platform with compounding value.

9 Reasons Why We’re Laser-Focus On (PMAX) This Morning—Monday, September 28, 2026…

1. Approx. 280% Move In September: (PMAX) shares moved from roughly $0.75 to $2.86 within a single month — a move exceeding 280% (approx.) which suggests the market is beginning to reassess the scope and pace of the company's transformation.

2. Small-Float: With less than 1.5M shares listed as available to the public, (PMAX)’s small float could witness the potential for big moves if demand begins to shift.

3. First Acquisition Is Already Revenue-Positive: The Boston Solar LOI targets a 13-year-old, vertically integrated business with $24M in annual revenue, 22% year-over-year growth, and approximately $2M in adjusted net income — a cash-flowing anchor for the broader platform.

4. $17M PIPE Funds the Acquisition Strategy: The capital raise completed in January 2026 provides funded capacity to close on the announced deal and pursue the next wave of accretive acquisitions at 3x–6x EBITDA.

5. Institutional-Grade Client Roster: Boston Solar's verified client list — including Fenway Park, MGM Music Hall, and a large federal agency — demonstrates commercial credibility and the ability to win high-profile contracts.

6. AI/NLP Platform With Defensive IP: The unnamed AI acquisition target holds 12+ patents, delivers 20x faster insights at 96% accuracy, and has been cited by five of the world's largest technology companies — creating a defensible moat with cross-portfolio deployment potential.

7. 30+ Combined Patents Across the Portfolio: The full pipeline targets more than 30 combined patents — including 12+ NLP patents and 20+ IoT patents — establishing durable barriers to entry across multiple verticals.

8. Solar Market Backed by Secular Growth: According to Grand View Research, the U.S. residential solar PV market is expanding at a 14.4% CAGR through 2030 — a long-duration tailwind for Boston Solar and the broader energy vertical.

9. IoT Division Already Deployed at Scale: The safety and sensing platform has shipped 30,000+ units across 40+ countries, carries 20+ patents, and reports gross margins above 50% — a high-margin, IP-protected business with global traction.

We’re Laser-Focused On (PMAX) This Morning…
Inline Image

Powell Max (NASDAQ: PMAX) has assembled the capital, the leadership, and a pipeline deep enough to build something that didn't exist a year ago — a multi-vertical holding company with 30+ patents, a revenue-generating first acquisition, and an AI layer that could tie the entire platform together.

The execution risk is real — roll-ups require discipline, and preliminary discussions are not closed deals.

But the structural setup — a named first target with $24M in revenue, a funded balance sheet, an active pipeline across five verticals, and a float of just 1.5M shares — creates the kind of profile that research-driven readers will want to examine closely.

The gap between what this company was twelve months ago and what it's becoming is where the story lives right now…

We have all eyes on Powell Max Limited (NASDAQ: PMAX) this morning.

Get laser-focused on (PMAX) while it’s still early.

Sincerely,

Paul Prescott
Co-Founder & Managing Editor
Street Ideas Newsletter

Street-Ideas.com (“Street-Ideas” or “SI” ) is owned by 147 Media LLC, a single member limited liability company. Data is provided from third-party sources and SI is not responsible for its accuracy. Make sure to always do your own research and due diligence on any day and swing profile SI brings to your attention. Any emojis used do not have a specific defined meaning, and may be used inconsistently. We do not provide personalized in-vest-ment advice, are not in-vest-ment advisors, and any profiles we mention are not suitable for all in-vest-ors.

Pursuant to an agreement between 147 Media LLC and TD Media LLC, 147 Media LLC has been hired for a period beginning on 09/27/2026 and ending on 09/28/2026 to publicly disseminate information about (PMAX:US) via digital communications. Under this agreement, TD Media LLC has paid 147 Media LLC seven thousand five hundred USD (“Funds”). These Funds were part of the twenty five thousand USD funds that TD Media LLC received from a third party named Interactive Offers LLC who did receive the Funds directly or indirectly from the Issuer and does not own stock in the Issuer but the reader should assume that the clients of the third party own shares in the Issuer, which they will liquidate at or near the time you receive this communication and has the potential to hurt share prices.

Neither 147 Media LLC, TD Media LLC and their member own shares of (PMAX:US).

Please see important disclosure information here: https://street-ideas.com/disclosure/pmax-Rgpt8/#details

(Nasdaq: COSM) Posted Record Revenue In Every 2026 Reporting Quarter So Far


Any content you receive is for information purposes only. Always conduct your own research.

*Sponsored

(Nasdaq: COSM) Posted Record Revenue In Every 2026 Reporting Quarter So Far


*Click Here To Get Our Alerts Faster Via SMS*


September 28th

Greetings Readers,


Two agreements. Under two weeks. Roughly 7.7Mn units of new contracted production for one factory in Athens, Greece.


That is the scoreboard Cosmos Health Inc. (Nasdaq: COSM) posted when its Cana Laboratories subsidiary signed five-year agreements with Target Pharma covering approximately 5.2Mn units of a topical antibiotic and an acne treatment.


Those contracts pushed Cana's cumulative orderbook past 32.7Mn units, a 31% increase since June.


They arrived just days after a separate five-year agreement with Viofar added about 2.5Mn units of ROSARTIA, a rosuvastatin-based cholesterol medicine.


Cana's contracted work now spans 11 therapeutic categories, up from nine.


Why does that matter?


Contract manufacturing turns a plant the company already owns into recurring, scheduled output.


According to the Target Pharma announcement, the division is targeted to generate over $10Mn in recurring annual pro-fit at full capacity, with some agreements extending up to ten years.


The factory story sits inside a wider turnaround. Cosmos reported record revenue in every 2026 reported quarter, including Q2 revenue of $18.99Mn, up 28.8% year over year, and first-half revenue of $36.91Mn, up 29.7%.


Management reaffirmed full-year 2026 guidance of more than $90Mn.


The balance sheet moved in the right direction too. Total liabilities fell 13.3% to $40.79Mn in the first half, while shareholders' equity rose 12.2% to $20.67Mn.


Then Cosmos repaid its $8Mn ATW convertible note twelve months ahead of maturity, ending further conversions from that instrument.

Behind The Numbers: What Management Is Saying


COSM CEO Greg Siokas did not dress up the September contract run. Here is how he framed it in the company's orderbook update:


“We have added 7.7Mn contracted units this month alone and grown the orderbook 31% since June, and close to threefold since the start of the year.”


He went further, noting that established pharmaceutical companies are choosing Cana because it built a facility that meets their standards. His summary line: every agreement "turns infrastructure we have already paid for into long-term, contracted production at attractive margins."


Siokas is also putting his own capital behind the plan. The company reports he added more than 7.8Mn shares in 2026, bringing his total holding to 14.6Mn shares.

The Pivot: From Distributor To Manufacturer Of Record


Cosmos built its name distributing medicines to Greek pharmacies. Today, the manufacturing arm is carrying more of the load.


Cana runs a wholly owned 54,000-square-foot facility in Athens, licensed under European Good Manufacturing Practices and certified by the European Medicines Agency.


The company has put approximately $5.5Mn into upgrading the site, including a new ACG capsule-filling line.


The result is visible in the orderbook.


It has grown from over 12Mn units earlier this year to more than 32.7Mn today, with partners such as Pharmex, which signed a five-year agreement for approximately 2.86Mn units.

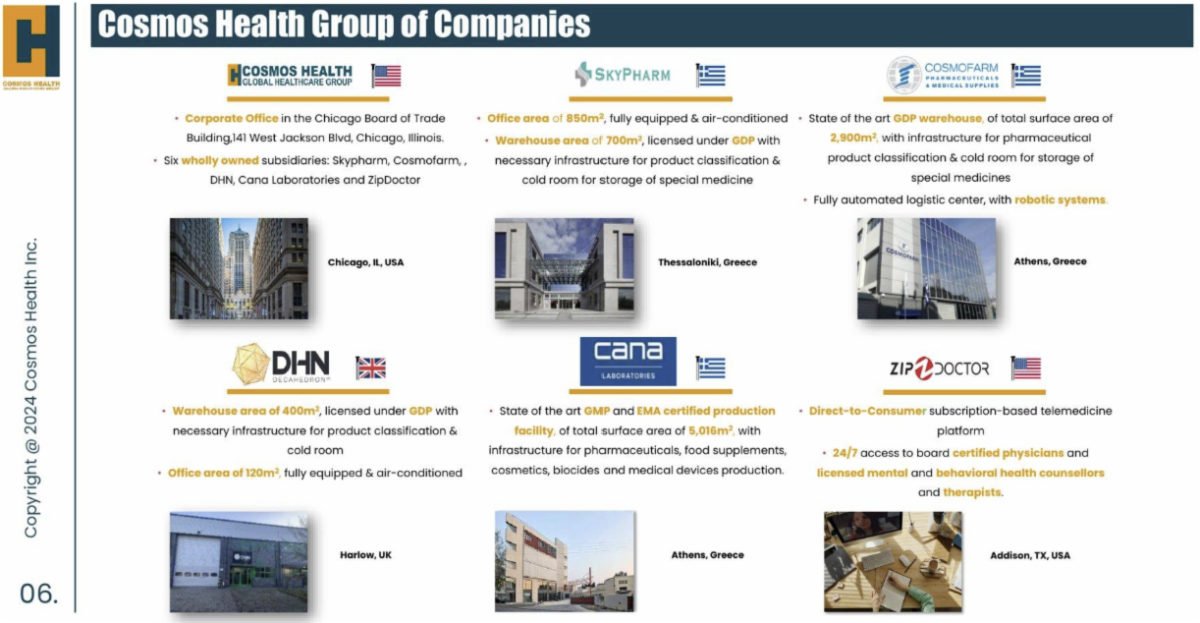
Cosmos Health's operating footprint spans Chicago, Greece, the UK, and Texas. Source: Cosmos Health company presentation

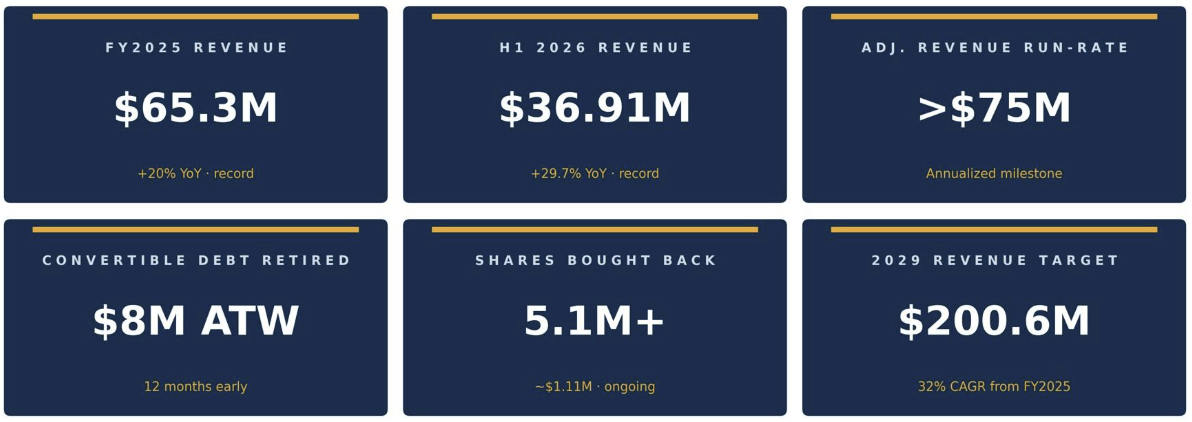
Key 2026 figures highlighted by the company. Source: Cosmos Health corporate update via GlobeNewswire


About Cosmos Health Inc. (Nasdaq: COSM)


Cosmos Health Inc. is a diversified, vertically integrated global heal-thcare group with offices and distribution centers in Greece and the UK.


It owns proprietary brands including Sky Premium Life, Mediterranation, bio-bebe, C-Sept, and C-Scrub.


The business runs on four engines, per the company's year-to-date update.


CosmoFarm supplies pharmacies and posted a record Q2 above $15Mn. Cana Laboratories handles manufacturing. Decahedron nearly doubled UK revenue in Q2. In the U.S., the 18 Series nutraceutical line (Cur18, Liv18, Oliv18 and Fort18) and NOOR Collagen target combined annualized revenue above $22.7Mn.


Cosmos has also signed letters of intent to acquire an $11.5Mn pharmacy distribution network and Doc Pharma S.A., an affiliated GMP manufacturer.

Sector Watch: Why Contract Manufacturing Draws Attention


Pharmaceutical companies increasingly hand production to specialist plants.


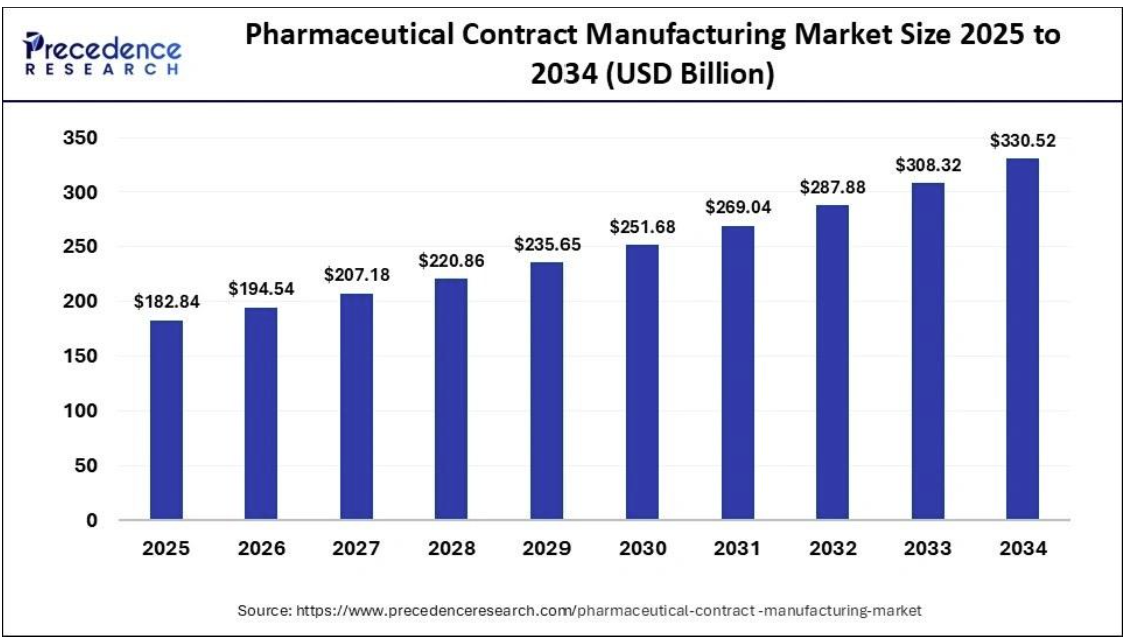
Precedence Research estimates the global pharmaceutical contract manufacturing market at $194.54Bn in 2025, on a path to approximately $351.55Bn by 2034, a 6.76% compound annual growth rate.


The firm expects the small and mid-sized pharmaceutical company segment to expand at the fastest pace.

Pharmaceutical contract manufacturing market outlook, 2025 to 2034. Source: Precedence Research


For a plant with EU licensing and spare capacity, that backdrop matters. Every new contract spreads fixed costs across more units.

6 Potential Catalysts Putting (Nasdaq: COSM) On Our Watchlist


#1. Contracted Orderbook Now Tops 32.7Mn Units. With agreements extending up to ten years, management at (COSM) has long-dated visibility into production volumes at its Athens plant.


#2. Record Revenue Delivered In Every 2026 Reporting Period. Q2 revenue climbed 28.8% to $18.99Mn, and (COSM) has reaffirmed full-year 2026 guidance above $90Mn.


#3. Convertible Note Retired A Full Year Ahead Of Schedule. By repaying the $8Mn ATW note early and withdrawing its shelf registrations, (COSM) removed a key source of potential dilution.


#4. Technical Signals Have Swung Sharply Over The Past Month. Barchart showed 8 of 13 indicators flashing bullish for (COSM) at Friday’s close, with an overall 24% bullish reading versus 100% bearish one month earlier.


#5. Insiders Hold More Than One Fifth Of Shares. Yahoo Finance data shows insiders hold approximately 21.68% of (COSM), and the CEO has added more than 7.8Mn shares in 2026.


#6. Zacks Coverage Carries A $4.50 Price Target. Zacks Small-Cap Research initiated coverage of (COSM) this year with a $4.50 target. That target hints at a potential upside over 400% from Friday’s close.

The Bottom Line


Cosmos Health Inc. (Nasdaq: COSM) is building something that is easy to overlook from the outside: contracted, repeatable production inside a factory it already owns.


Add record revenue, a lighter balance sheet and a CEO who keeps adding shares, and you have a name worth tracking closely.


With a current market capitalization around $36Mn on 9/25/26, and trailing twelve month revenue of about $73.73Mn, per Yahoo Finance, COSM has grabbed our full attention.


We’re initiating coverage on Cosmos Health Inc. (Nasdaq: COSM).


Be on the lookout for updates heading out shortly. Talk soon.


Sincerely,

Kai Parker

StockWireNews


(Always Remember The St-ock Prices Could Be Significantly Lower Now From The Dates I Provided.)


*StockWireNews.com (“StockWireNews” or “SWN” ) is owned by SWN Media LLC, a single member limited liability company. Data is provided from third-party sources and SWN is not responsible for its accuracy. Make sure to always do your own research and due diligence on any day and swing profile SWN brings to your attention. Any emojis used do not have a specific defined meaning, and may be used inconsistently. We do not provide personalized in-vest-ment advice, are not in-vest-ment advisors, and any profiles we mention are not suitable for all in-vest-ors.


Pursuant to an agreement between SWN Media LLC and TD Media LLC, SWN Media LLC has been hired for a period beginning on 09/27/2026 and ending on 09/28/2026 to publicly disseminate information about (COSM:US) via digital communications. Under this agreement, TD Media LLC has paid SWN Media LLC seventeen thousand five hundred USD ("Funds"). To date, including under the previously described agreement, SWN Media LLC has been paid thirty five thousand USD ("Funds"). These Funds were part of the twenty five thousand USD funds that TD Media LLC received from a third party named Kilwater Capital LLC who did not receive the Funds directly or indirectly from the Issuer and does not own st-ock in the Issuer but the reader should assume that the clients of the third party own shares in the Issuer, which they will liquidate at or near the time you receive this communication and has the potential to hurt share prices.


Neither SWN Media LLC, TD Media LLC and their member own shares of (COSM:US).


Please see important disclosure information here: https://stockwirenews.com/disclosure/cosm-zaizp/#details

Share With Friends

Bookmark and Share
 
recipes for healthy food © 2008 | Créditos: Templates Novo Blogger