Any content you receive is for information purposes only. Always conduct your own research.
*Sponsored
Cemtrex, Inc. (Nasdaq: CETX) Just Landed On The Top Of The Market Crux Watchlist This Morning
—Thursday, September 17, 2026…
Don’t Miss Our Next Update—Get Real-Time Alerts Sent Directly To Your Phone. Up To 10X Faster Than Email. Get Focused On (CETX) While It’s Still Early…
September 17, 2026 Dear Reader, The clock is ticking toward the opening bell, and one industrial technology company is giving us several reasons to pay attention. Its 2026 expansion has been aggressive, while the latest operating numbers are beginning to show measurable progress. Something worth paying attention to is happening in the industrial sector right now… The defense budget is expanding. Reshoring is accelerating. Infrastructure spending keeps climbing. And critical-facility security — prisons, government buildings, healthcare campuses — is seeing a surge in modernization demand that shows no signs of letting up. These aren't isolated trends. They're converging — and the companies that sit at the intersection of all three are the ones most likely to benefit as capital flows through the system. At the center of these converging trends, one Nasdaq-listed company has completed three acquisitions in a single calendar year, launched an entirely new Aerospace & Defense segment, watched its equity base nearly quadruple, and started converting that expansion into positive operating cash flow. The company is Cemtrex, Inc. (Nasdaq: CETX). And the closer you look at the operational trajectory unfolding here, the more the numbers start to demand attention… Cemtrex, Inc. (Nasdaq: CETX) is topping our watchlist this morning—Thursday, September 17, 2026. 
Keep in mind, (Nasdaq: CETX) has a float less than 2M shares listed as available to the public—with a float that small, the potential exists for big moves if demand begins to shift.
Three Segments, Three End Markets, One Small FloatThe first thing to know about Cemtrex, Inc. (Nasdaq: CETX) is that it operates across several different businesses, not just one product or service. It's a diversified operating platform running across three segments — Security, Industrial, and Aerospace & Defense — each generating its own revenue, serving its own customer base, and riding its own secular tailwind. The Security segment operates through Vicon Industries, a decades-old name in video management software, high-performance cameras, and integrated surveillance solutions serving government, corrections, and enterprise customers. That matters because the demand behind video surveillance is real and accelerating… According to Grand View Research, the global video surveillance market was estimated at $83.48B in 2025 and is projected to reach $204.68B by 2033 at an 11.7% CAGR. 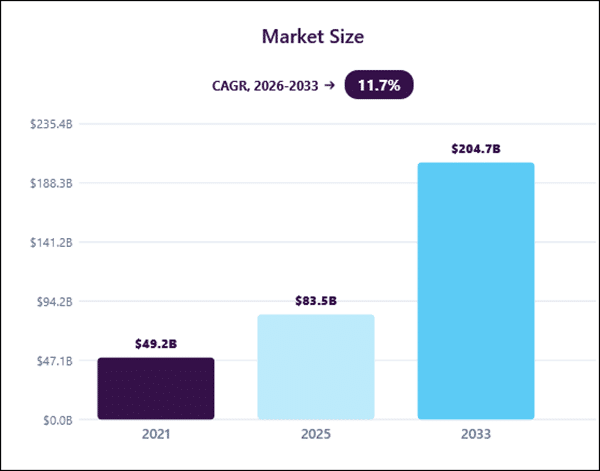
Vicon sits directly in that growth path. And the orders are landing. Since May, Vicon has announced approximately $2.9M in corrections-related orders, including a $900K single-facility award covering the complete Vicon platform — cameras, servers, workstations, software — deployed end-to-end through a specialist detention integrator. 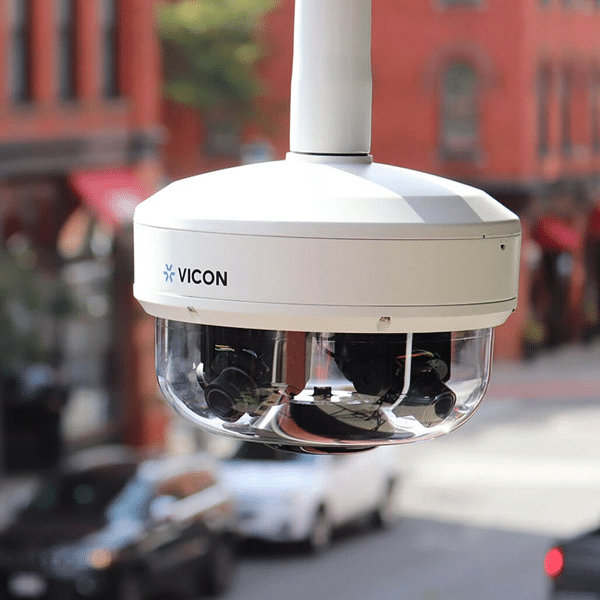
Corrections is one of the most demanding end markets in physical security. Systems run continuously for years in hardened environments, and integrators who concentrate an entire facility on a single vendor do so only when they trust that vendor completely. That kind of full-platform commitment from a single customer — every camera, every server, every screen on one system — speaks louder than any quarterly guidance. The Industrial segment, operated through Advanced Industrial Services (AIS), delivers specialized rigging, millwrighting, piping, and equipment installation for manufacturers nationwide. AIS has grown from approximately $21M to $38M in annual revenue between FY2022 and FY2025. That's a near-doubling in three years — steady, compounding expansion built on a high-repeat customer base across infrastructure end markets. With reshoring trends accelerating and domestic manufacturing capacity expanding, AIS sits in the direct path of multi-year capital deployment. These are the kinds of services — rigging heavy equipment, installing production lines, maintaining complex manufacturing infrastructure — that don't get offshored and don't get automated. Somebody has to physically put the machines in place. AIS does that work. And then there's the segment that could change the math entirely. The Aerospace & Defense segment, anchored by Invocon, brings a 40-year-plus engineering heritage in mission-critical instrumentation, wireless sensing, and telemetry for space and missile programs. Invocon counts the Missile Defense Agency and major defense primes among its customers. In April 2026, the subsidiary was selected for a U.S. Navy SBIR Phase I contract in naval mine warfare. That's not a press release talking point. That's the Department of Defense validating a capability — and potentially opening a pipeline of follow-on work in an area where program continuity and institutional trust matter more than the initial contract value. Phase I work, by design, is meant to demonstrate feasibility before larger Phase II funding follows.
Three Deals Done — And A Fourth On The Way
What separates (CETX) right now is the velocity of its platform expansion. In calendar 2026 alone, the company has completed three acquisitions… Invocon closed in January for $7.1M in cash, launching the Aerospace & Defense segment from scratch. Richland closed in February, extending AIS's geographic footprint into Tennessee and the Southeast. And in July, Plant Engineering Services (PES) joined the platform — adding the engineering expertise that sits upstream of AIS's installation, rigging, and millwrighting work. PES specializes in the design, modernization, and relocation of large hydraulic and mechanical press systems for aerospace forging, automotive, defense, and heavy manufacturing. Founded more than thirty years ago, PES is expected to contribute $4–5M in revenue over the next twelve months. The combination creates something the two companies couldn't offer on their own… AIS can now pursue turnkey capital projects — from engineering and design through installation and commissioning — under a single platform. Chairman and CEO Saagar Govil described the fit directly: "PES brings deep engineering expertise that AIS has never had in-house, and AIS brings the field execution resources that PES has historically sourced externally. Each company is a natural customer of the other." And perhaps the most telling signal of all… An additional Industrial Services deal is currently under letter of intent and targeted for the September quarter. Four completed deals in a single fiscal year would represent a cadence that signals real intent — a management team actively compounding a platform, not just presenting slides about one. And because all three acquisitions were done with corporate overhead essentially unchanged from FY2025, each new segment's earnings compound against a fixed cost base. That's the kind of operating structure where scale creates meaningful margin expansion as the platform grows. The Q3 Numbers Tell The Real Story
What makes the timing worth watching is that the most recent quarterly results confirm operational momentum building across the entire company. For Q3 FY2026, Cemtrex, Inc. (Nasdaq: CETX) reported revenue of $18.4M, up 9% year-over-year and 2% sequentially — marking a return to consolidated top-line growth. The Aerospace & Defense segment delivered $2.2M in Q3 revenue with $1.0M in segment operating income on 87% gross margins — in only its second quarter of consolidation. Vicon's segment operating loss narrowed to $0.3M from $3.0M in Q1 — a 90% improvement across two quarters, with gross margins climbing to 49%. That's a security business approaching breakeven after a complete cost restructuring. Operating EBITDA improved by $1M sequentially… And operating cash flow turned positive during Q3 at $0.2M — a meaningful shift from the $5.1M used in operations during the first half of the year. The balance sheet tells the same story. Shareholders' equity now stands at $32M, up from $8.7M at fiscal year-end — nearly four times the starting figure. Cash and marketable securities totaled $11.7M as of June 30, 2026. These aren't projections on a slide deck. These are reported figures showing two consecutive quarters of sequential improvement across the platform. And here's what connects the balance sheet to the acquisition strategy… With $11.7M in cash and securities and a strengthened equity base, the company has the financial capacity to keep compounding — and management has already said it intends to maintain this pace of acquisitions into FY2027 and beyond. 7 Reasons Why We’re Focused On (CETX) This Morning—Thursday, September 17, 2026…
1. Small-Float: With less than 2M shares listed as available to the public, (CETX)’s small float could witness the potential for big moves if demand begins to shift. 2. Three-Segment Diversification: The company operates across Security, Industrial, and Aerospace & Defense — three independent end markets with separate revenue streams and secular growth drivers. 3. Aerospace & Defense Delivering: Invocon posted $2.2M in Q3 revenue with $1.0M in operating income on 87% gross margins and was selected for a U.S. Navy Phase I contract in its first year under the (CETX) umbrella. 4. Security Approaching Breakeven: Vicon's operating loss narrowed 90% from Q1 to Q3 with Q3 gross margins of 49%, and roughly $2.9M in corrections orders have been announced since May. 5. Acquisition Velocity: Three deals completed in calendar 2026 with a fourth under LOI for the September quarter. PES alone is expected to add $4–5M in revenue over twelve months while opening automotive and defense manufacturing end markets. 6. Cash Flow Inflection: Operating cash flow turned positive in Q3 following $5.1M used in the first half, with Operating EBITDA improving $1M sequentially — the second straight quarter of consolidated operating improvement. 7. Surveillance Market Tailwind: The global video surveillance market is projected to grow from $83.48B to $204.68B by 2033 at an 11.7% CAGR per Grand View Research, providing a durable macro backdrop for Vicon's government and enterprise surveillance platform. Get Focused On (CETX) While It’s Still Early… 
When you stack it all up — a diversified three-segment platform, sequential improvement across the business, new government defense contracts, a compounding acquisition pipeline, and a float under 2M shares — (CETX) presents a profile that warrants closer attention. The company reported $76.5M in revenue last fiscal year… It's actively expanding into defense, automotive, and critical infrastructure end markets… The Q3 trajectory shows real sequential progress — and with PES now onboarded, a fourth deal in the pipeline, and the Navy contract opening new doors for Invocon, the runway ahead looks longer than the road behind. Anyone following the industrial and defense space should have this name on their radar. We’re focused on (CETX) this morning with under 90 minutes to go before the bell. Keep an eye out for our next update, it could be coming very shortly. Sincerely, Gary Silver Managing Editor, MarketCrux |


0 التعليقات:
إرسال تعليق