|
A loud week: a forced buying spree, a superpower summit, an oil scare. Under all of it the 10-year Treasury climbed to its highest since 2007, and that quiet number moved your portfolio more than any of the noise.
| |
|
|
|
September 25, 2026 • Friday edition • No hype, just perspective.
|
|
A Rebalance, a Summit, an Oil Scare — and One Number Above Them All
This was a loud week. Index funds were forced to buy billions of a single stock, a Chinese leader came to the White House, and oil lurched on war-and-peace headlines. Under all of it, the 10-year Treasury yield climbed to its highest level since 2007, and that quiet number did more to your portfolio than any of the noise.
|
|
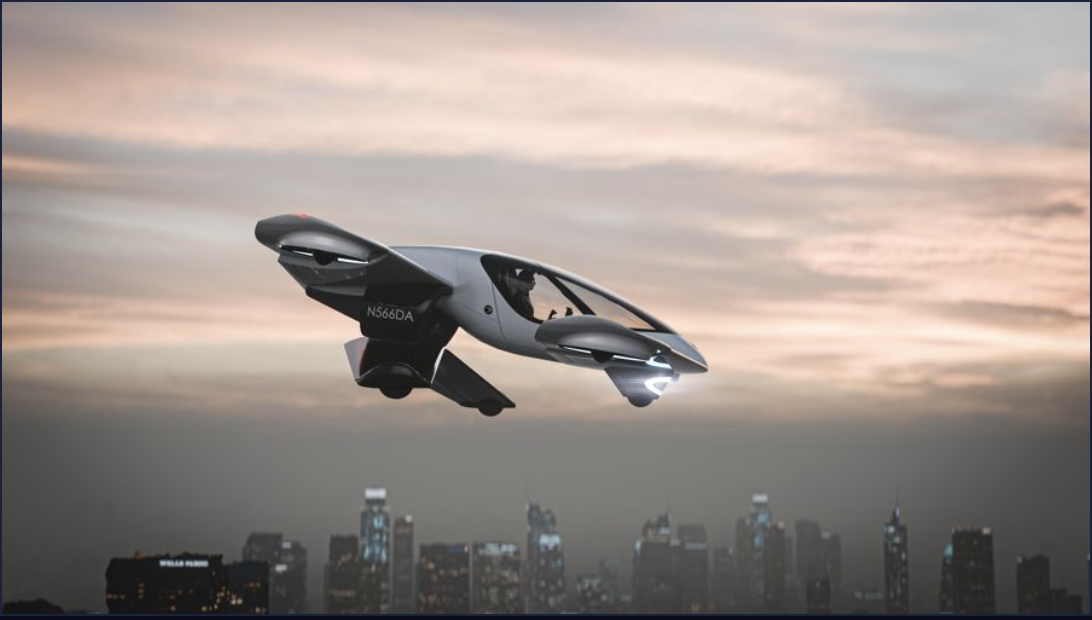 A Ticker Before the Runway Doroni has reserved the Nasdaq ticker $DRNI. It is a step toward a potential listing, not a confirmed one, and the company says so plainly. Behind the milestone is real work: a completed full-scale model and 70+ test flights, backed by an FAA certificate for testing. The company has raised $40M+ from 14,000+ investors. Shares are $3.30 today. Up to 20% bonus shares are available for a limited time. October 22 is the last day to lock in the $3.30 share price. What’s behind $DRNI → This is a paid advertisement for Doroni Regulation A offering. Please read the offering circular at https://invest.doroni.io/ |
|
|
The Week That Just Happened
|
• Monday: The SpaceX rebalance forced index funds to buy $15.5 to $22 billion of the stock at Friday’s close, and the S&P 500 rose 1.49 percent to near a record on AI and chip strength.
• Tuesday: Stocks pushed to the edge of new highs while the 10-year Treasury yield held above 5 percent for the first time since 2007, a warning the rally waved off.
• Wednesday: The warning landed. The S&P fell 0.8 percent as the 10-year jumped to 5.11 percent, a nineteen-year high, after a hot business-activity survey revived fears of another Fed hike.
• Thursday: President Xi came to the White House, and the two sides extended their trade truce by two months, to January 10. Markets barely moved.
• Friday: Jobless claims fell to 197,000, a sign of a still-hot economy, with the final read on consumer sentiment due at 10 a.m. after a preliminary 47.8, among the lowest ever.
|
|
|
Details
|
The loudest week in months came down to the bond market
Step back from the individual days and the week has a single spine. On Monday the market was celebrating. By Wednesday it was selling off. By Friday it had steadied. What changed in between was the price of money. The news was busy the whole week, but the yield was the part that mattered. The 10-year Treasury rate, the number that sits under every mortgage, every corporate loan and every stock valuation, climbed to 5.11 percent, a level it had not touched since 2007.
On Tuesday, this letter flagged that number and argued the bond market was the one to watch, even as stocks flirted with records. By Wednesday the point had made itself. A hot reading on business activity revived fears that the Fed is not finished raising rates, yields jumped, and the equity rally that had looked unstoppable on Monday rolled over. Jobless claims on Thursday, down to 197,000, only reinforced the picture of an economy still running warm enough to keep the Fed uneasy.
Even the week’s marquee event bent to the same force. President Xi’s visit produced a two-month extension of the US-China trade truce, now running to January 10, and warm words about stability. It was a de-escalation worth having, and the market barely blinked, because a truce does not touch the arithmetic that has yields climbing: a government issuing record amounts of debt into a world that keeps demanding more to hold it.
Early-stage investing normally forces a trade. Early means cheap and unproven. Proven means expensive and usually public. You rarely get both. Green Coffee Company sits in the narrow space between them. It is early enough to still be private and priced at $1.10 a share, with a round open to ordinary investors. It is also already operating at scale, in a way most private companies at this price are not. The scale is specific. 45 farms in Colombia. Around 10 million coffee trees. $26M in 2025 revenue, up from $1M in 2021. Coffee on 3,000+ shelves across 21 states, in Target and Walgreens. Exclusive U.S. and Canada rights to Juan Valdez. That combination — private pricing, public-shelf reality — is the reason it is worth a closer read rather than a quick dismissal. It is still a private, illiquid, speculative position. Returns are not guaranteed, and you could lose the full investment. The point is not that it is safe. It is that “early” here does not mean “hypothetical.” Unpack why it’s still private → Private investments are speculative and illiquid. Returns are not guaranteed. Review the offering circular before investing. Under Regulation A, a company may change its share price by up to 20% without requalifying the offering with the Securities and Exchange Commission. |
What this means for your portfolio. If you hold a standard 60/40 mix, this week was a quiet lesson in why the “safe” 40 has not felt safe. As yields rise, the price of existing bonds falls, so the fixed-income sleeve that is supposed to cushion you has been losing value even while it pays more interest. The other side of that coin is that cash and short-term Treasuries now yield more than 4 percent with almost no risk, which for the first time in years gives a patient investor a real alternative to reaching for stocks. None of this calls for overhauling a retirement plan around a single week. The useful step is to know how much of what you own depends on rates coming back down, because at a nineteen-year high, they are in no hurry to.
Next week, the numbers that matter. The calendar ahead holds the release the Fed cares about most. On Wednesday, September 30, the government publishes the PCE price index, the inflation gauge the Fed watches above all others, and after this week’s hot activity data a firm reading would harden the case for another rate rise at the October 27-28 meeting. The same morning brings earnings from Micron, a bellwether for the memory chips feeding the AI build-out. Watch the inflation print first. If prices are still sticky, the 10-year that drove this week may have further to climb, and the pressure that cracked the rally on Wednesday will still be in the room.
This week arrived dressed as a run of big events: a forced buying spree, a superpower summit, an oil scare. It leaves as a single number, a 10-year Treasury yield at a nineteen-year high, quietly resetting the cost of everything you own and owe. Next Wednesday’s inflation reading will say whether that number is finished climbing. Until then, the loudest thing in this market is also the quietest one.
|
|
Harold Winston
Thirty years reading markets for a living.
No hype, just perspective.
|
|
|
|


0 التعليقات:
إرسال تعليق