Key Points
- NVIDIA is reportedly exploring a deal to acquire or expand its stake in Reflection AI, a startup building open-weight foundation models and agentic tools.
- Such a deal would likely reinforce NVIDIA's hardware-centric moat rather than shift its strategy, though it could draw regulatory scrutiny similar to its Groq arrangement.
- With a consensus Buy rating from 55 analysts and roughly 40% implied upside, NVIDIA heads into its Nov. 18 earnings report amid decelerating but still strong growth forecasts.
- Special Report: The Rumors About Elon’s Next Move Are Spreading Fast
Being AI-lab agnostic has long been a pillar of NVIDIA’s (NASDAQ: NVDA) strategy. Selling to all labs creates a deep moat, making the question of which one wins moot: NVIDIA always wins because it sells hardware, ecosystems, and services to the industry. As it stands, the moat is based largely on silicon, but it deepens with every advancement along the stack, entrenching its position as a comprehensive, universal AI developer ecosystem.
So, what happens when the company breaks out of its mold? Speculation is running rampant that this is becoming increasingly likely. NVIDIA is reportedly in early talks to buy Reflection AI or increase its investment in the startup. Reflection AI is a newer startup founded by former Alphabet (NASDAQ: GOOGL) DeepMind researchers.
Reflection AI focuses on open-weight foundation models (which aren't necessarily fully open-source) and agentic software tools that democratize AI. Governments, enterprises, and AI labs can download the software, own it, customize it, and run AI models on their own hardware. Offerings include Beam, focused on coding, reasoning, and agentic tasks, and Asimov, an agentic tool that helps developers answer complex questions about software systems.
NVIDIA’s Moat Will Deepen If It Acquires Reflection AI
Investors should note that this move wouldn't necessarily alter NVIDIA's strategy; it could strengthen it. Owning a developer of open-weight AI tools helps NVIDIA deepen its moat. Making AI models more widely accessible keeps the focus on its hardware and ecosystem, not which model developer wins.
The likely outcome is that modelers and, more importantly, inference providers will keep investing in NVIDIA technology as demand for AI-enabled enterprise and consumer services grows. It's not about the models but the equipment you use to run them. Models are already a dime a dozen; the question for businesses and consumers is which ones to use and how to access them. This move could cement, secure, and strengthen NVIDIA’s revenue and earnings outlook as the AI industry expands.
And NVIDIA isn’t new to the business. NVIDIA previously an $800 million direct investment in Reflection AI, anchoring a $2 billion funding round, which valued the company at $8 billion. The partnership not only provides the company with money but also strengthens its ties to NVIDIA's GPU ecosystem, which Reflection AI uses to train its models. Nebius Group (NASDAQ: NBIS) is another critical player, having secured a $1 billion contract from Reflection AI for cloud capacity and services.
The question of whether owning a model maker gives NVIDIA a new revenue stream or strains its relationships with AI labs remains open. NVIDIA may be more interested in Reflection AI for its position in the AI ecosystem than for its revenue. If NVIDIA wants to keep low-cost, open-weight AI models in Western control, an acquisition could be strategically valuable. The risk is that China emerges as the leader in low-cost models, leading the industry toward its hardware and ecosystem rather than NVIDIA’s.
NVIDIA Will Control Reflection AI, the Only Question Is How?
The most important question is: How might the deal be structured? Investors should consider the possibility of a non-standard workaround, such as a hire-to-acquire strategy, but even that is not assured. NVIDIA may simply hire Reflection AI’s staff and license its technology, potentially avoiding a lengthy merger review without necessarily escaping regulatory scrutiny.
Regulatory oversight also poses risks, as authorities have already expressed interest in other deals. NVIDIA licensed technology from Groq and hired several of its executives (also started by Alphabet engineers) in a similar manner, raising questions from lawmakers about whether it intentionally avoided regulatory oversight.
Those raising concerns include Senators Elizabeth Warren and Richard Blumenthal, who argue that NVIDIA’s AI dominance may pose a threat to competition. In this environment, the company will have to be careful to address regulatory concerns.
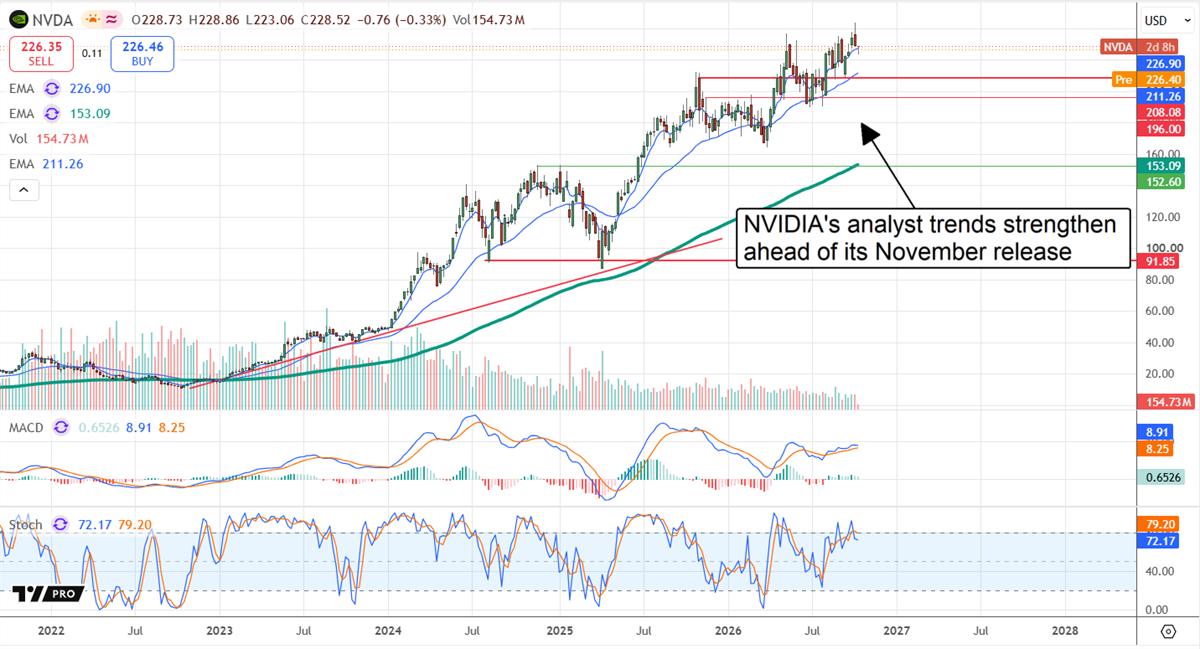
Analysts remain bullish on NVIDIA, although the impact of the potential deal remains uncertain. The acquisition could represent an extension of NVIDIA's strategy rather than a strategic shift. The stock carries a consensus Buy rating from the 55 analysts tracked by MarketBeat, with a consensus price target suggesting over 40% upside from mid-October trading levels.
NVIDIA’s next visible catalyst is its upcoming earnings report. Expected around Nov. 18, analysts forecast a deceleration to about 90% year-over-year revenue and earnings growth. The company consistently outperforms estimates and could do so again this quarter. Global investment in AI infrastructure across industries continues to drive demand for its core products. Investors will be watching growth, as well as profitability, cash flow, and capital returns, which have been accelerating.
Read this article online ›
The best investment opportunities don't wait. Get our research and stock ideas delivered straight to your smartphone—so you never miss a market-moving opportunity. Our text alerts ensure you see timely stock ideas and professional research reports instantly, whether you're in a meeting, commuting, or away from your desk.
Get Text Alerts from American Market News (free)


0 التعليقات:
إرسال تعليق