Investors Sold the Wrong Side of This DealBy Joel Litman, chief investment officer, Altimetry
 French energy-technology giant Schneider Electric (SU.PA) just made the biggest bet in its 190-year history...
And investors hated it. On October 5, Schneider agreed to buy U.S. software maker PTC (PTC) for about $22.6 billion. That's $205 a share, a 42% premium over PTC's last close before the deal. Schneider's stock fell nearly 10% that morning in Paris, wiping out about $17 billion of market value. And it kept sliding. Shares are now down about 17% from their close the Friday before the announcement. Shares of Schneider that trade over the counter here in the U.S. under the ticker SBGSY have fared even worse... They're down more than 20% from their preannouncement price. The market has many reasons for its pessimism. Schneider is paying a huge amount – at a hefty premium – for a software business... Software is the one corner of the market investors have spent most of this year running from. But a big premium doesn't mean it's a bad deal. And as we'll explain today, we believe the market has it wrong. Schneider just bought a business twice as profitable as its own... at a price that doesn't require further growth. Schneider got its start in iron manufacturing...Today, it sells the cooling systems, server racks, and power gear that keep data centers running. That business is now the main driver of its earnings. PTC, meanwhile, makes software that manufacturers use to design products on a computer screen and then manage them through production and repair. Schneider CEO Olivier Blum, who took over in late 2024, says PTC's engineering data will help Schneider put AI to work inside its customers' factories. And once the deal is complete, recurring software sales will account for about 24% of Schneider's total sales. The market's widespread software panic gave Schneider a rare opportunity...Early this year, investors started dumping software stocks en masse. They feared AI tools would let companies do more on their own, reducing the need for paid subscriptions. Roughly $1 trillion in software market value vanished between mid-January and mid-February alone as investors jumped ship.
| Recommended Links: |
|
 Elon's iPhone Killer The analyst who briefed Congress on the iPhone years in advance has uncovered a surprising paper trail, which he believes proves Elon Musk's next big move. Check out the new FCC ruling... two trademarks filed on the same day... and the multibillion-dollar spectrum acquisitions and chip deals... all of which point to a new device unlike anything Musk has released before. Get the full story here. |
|
|
PTC got swept up in the sell-off. Its stock peaked at $217 in August 2025, then bottomed out at $112 this June... a drop of nearly half. Schneider stepped in while PTC was still well off its highs. Even with the 42% premium, the energy-tech giant is paying less than what PTC traded for last summer. Global investment bank Jefferies told clients that thanks to the software sell-off, Schneider is buying PTC at its lowest valuation in a decade. PTC is a far more profitable business than the one buying it...In fiscal 2019, PTC finished moving its customers from one-time license purchases to recurring subscriptions. Since then, steady subscription payments have turned it into a cash machine. Its Uniform return on assets ("ROA") climbed from 15% that year to 53% in fiscal 2025. That means PTC produced 53 cents of Uniform earnings for every dollar of assets. Now, Schneider is a strong business, too. Its Uniform ROA has stayed between 18% and 26% for the past decade. Today, the figure sits at 24%... about 2 times the corporate average. Still, PTC earns more than double what Schneider does on every dollar of assets. That means Schneider is acquiring a business that generates substantially more earnings from its assets than Schneider does itself. And Schneider didn't pay for growth PTC hasn't delivered...We can see this through our Embedded Expectations Analysis ("EEA") framework. The EEA starts by looking at a company's current stock price. From there, we can calculate what the market expects from the company's future cash flows. We then compare that with our own cash-flow projections. In short, it tells us how well a company has to perform in the future to be worth what the market is paying for it today. At current prices, investors expect PTC's Uniform ROA to land around 51% by 2030. That's roughly where the ROA sits right now. It's also below the 60% analysts expect for the fiscal year that just ended. Take a look... 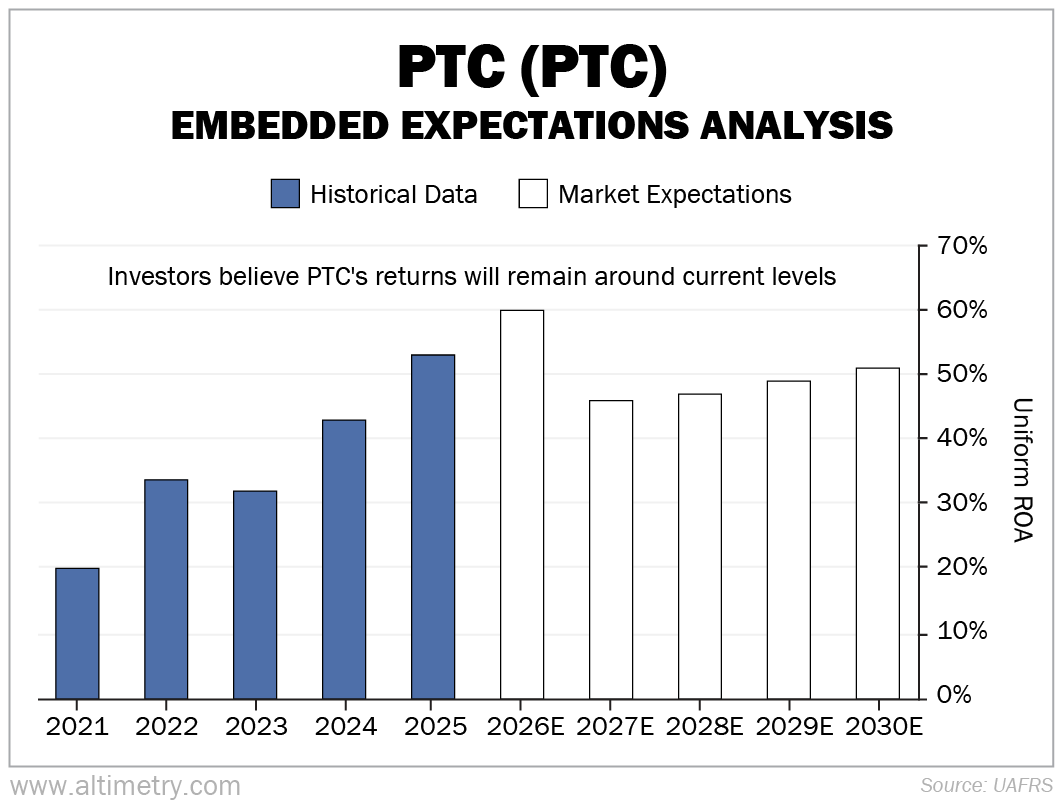
As you can see, the market expects PTC's returns to hold steady from here. At these prices, Schneider is paying for the business PTC already is – not for some pie-in-the-sky growth forecast. When a buyer shells out money for better returns, pay attention...Yes, Schneider is taking on €16 billion to €17 billion of new debt and issuing €5 billion to €6 billion of new shares to pay for PTC. That helps explain some of the market's skepticism. But Schneider bought a business that earns double its own returns, during a market sell-off, at a price that only asks PTC to keep doing what it's already doing. That should make Schneider a more profitable company over time... and it's a bullish signal for the stock. In the future, if a company you own announces a big acquisition, look past the premium and ask two questions... Does the acquisition target earn more than the buyer? And does the offer price require the target to get better? If the answers are "yes" and "no," respectively, and investors dump shares anyway, then that's their mistake... not proof that management got it wrong. Schneider passed that test. The market just hasn't noticed yet. If you're looking for places to put your money today, Schneider is a good option to consider while shares are still trading at lower levels. Regards, Joel Litman
October 20, 2026
|


0 التعليقات:
إرسال تعليق