Any content you receive is for information purposes only. Always conduct your own research. *Disseminated on Behalf of ZenaTech, Inc.
ZenaTech, Inc. (Nasdaq: ZENA) Lands On The Market Crux Watchlist This Morning—Wednesday, October 7, 2026
Don’t Miss Our Next Update—Get Real-Time Alerts Sent Directly To Your Phone. Up To 10X Faster Than Email. Pull Up (ZENA) While It’s Still Early… October 7, 2026 Dear Reader, When a company's revenue grows more than 13 times across seven consecutive quarters, that kind of trajectory tends to demand a closer look… ZenaTech, Inc. (Nasdaq: ZENA) just reported Q2 revenue of $9.3M (CAD) — a 316% year-over-year surge — and first-half revenue of $17.7M (CAD), up 425% from the same period last year. Not projected numbers. Not modeled assumptions. Actual, reported, audited results from a company executing an aggressive Drone as a Service roll-up strategy while simultaneously advancing a defense drone portfolio that spans counter-UAS interceptors, quantum navigation, and AI-powered autonomy. And here's the part that makes this worth watching right now… That revenue growth is accelerating, not plateauing. Seven consecutive quarters of sequential gains — each one building on the last — suggest this isn't a spike driven by a single contract or a one-time event. It's a compounding curve. Quarterly figures went from roughly $700K in Q4 2024 to $9.3M (CAD) in Q2 2026, according to the company's shareholder letter — and the DaaS segment alone generated nearly 93% of that total. That's a recurring-revenue engine, not a one-off windfall… When 93% of your quarterly revenue comes from a single scalable segment — and that segment is still adding new geographies and verticals with every acquisition — the math starts to speak for itself. Meanwhile, Maxim Group maintains a bullish rating on ZENA with a $5 target, suggesting meaningful upside from recent levels near $1.30 per Barchart historical data. And these are only some of the reasons why (Nasdaq: ZENA) is topping our watchlist this morning — Wednesday, October 7, 2026. 
The Roll-Up Engine Behind the Revenue Curve
The foundation of ZenaTech, Inc. (Nasdaq: ZENA)'s growth is its Drone as a Service platform — and it's scaling at a pace that deserves attention… The company has now completed 29 acquisitions of established land surveying, inspection, and service companies across the U.S., Canada, the UK, and Australia. Each acquisition adds existing customers, licensed professionals, and immediate revenue upon consolidation. That's the beauty of the model… Instead of building from scratch and waiting quarters for revenue to materialize, ZenaTech, Inc. (Nasdaq: ZENA) acquires companies that already generate cash flow, folds them into a centralized drone-enabled platform, and begins layering its proprietary AI and automation technology on top. 
DaaS operations now span 14 U.S. states, with the most recent acquisition — Georgia-based Merritt Paul Land Surveying — bringing licenses in 17 states and exposure to solar and railroad verticals. That's not a narrow niche — it's a platform reaching into energy infrastructure, transportation, and precision agriculture all at once. Signed acquisition offers at the time of Q2 results were expected to contribute approximately C$40M in additional first-year revenue following closing, per the financial results announcement. The balance sheet has strengthened in parallel — cash and marketable securities totaled $34.6M (CAD), total assets surpassed $149M, and in June 2026, ZenaTech, Inc. (Nasdaq: ZENA) was added to the Russell 3000® Index. That kind of index inclusion could open doors to broader institutional visibility as the company continues to execute. When a company goes from sub-$1M quarterly revenue to nearly $10M in less than two years and then gets added to a major benchmark index, the trajectory alone warrants a closer look at what's being built underneath. Defense Drones, Quantum Navigation, and a Counter-UAS Market Approaching $20B
While DaaS drives the near-term revenue curve, ZenaTech's defense technology pipeline could be the longer-term story that defines the company… The ZenaDrone 2000 heavy-lift interceptor — a gasoline-powered platform designed for more than four hours of hover endurance — is advancing through prototype assembly at ZenaTech's Sharjah, UAE facility, with flight testing expected to begin in Q1 2027. The system is designed to address a growing asymmetry in modern defense — nations spending hundreds of thousands per missile to neutralize hostile drones that could cost under $20,000. That cost mismatch has become one of the defining challenges of 21st-century defense… And it's exactly the kind of problem that creates demand for new platforms. CEO Shaun Passley, Ph.D., framed the significance clearly: "Militaries, navies and border agencies need counter-drone systems that can stay on station for hours and respond to many threats at once, at a cost they can field at scale," noting that industry analysts indicate the counter-UAS market could exceed USD $20B by 2030. The ZenaDrone 2000 isn't operating alone… The low-cost Interceptor P-1 has already entered flight testing, and together the two platforms are designed to give defense customers a layered system — the ZenaDrone 2000 watches and coordinates, while P-1 interceptors engage threats at a target cost of under $5,000 per unit. On the technology frontier, ZenaDrone has advanced a quantum navigation system into drone testing — a system enabling secure operations in GPS-denied environments where adversaries jam or spoof satellite signals. That's a capability with implications well beyond any single drone platform… And the company has been selected as a qualified supplier under Canada's Defence Drone Initiative Marketplace, creating a procurement pathway for future Canadian Armed Forces and Coast Guard drone requirements. Multiple drones in the ZenaDrone portfolio — including the ZenaDrone 1000, IQ Nano, and IQ Square — are also advancing through Blue UAS certification, which supports eligibility for U.S. government and defense procurement. That certification process matters — and here's why. Blue UAS approval is the gateway for drone manufacturers seeking to supply the U.S. Department of Defense and federal agencies — and having multiple platforms in the pipeline at once signals the kind of breadth that could establish (ZENA) as a multi-role defense drone provider rather than a single-product vendor. 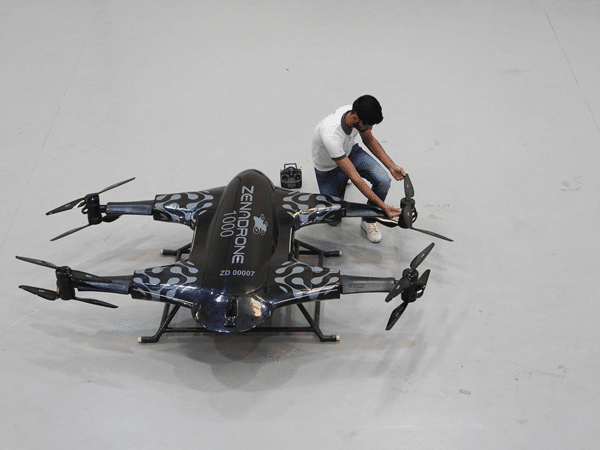
From Precision Agriculture to Enterprise Software — the Pipeline Keeps Expanding
The breadth of what ZenaTech is building extends well beyond defense… ZenaTech, Inc. (Nasdaq: ZENA) recently secured Irish Aviation Authority operational authorization for drone-based crop and soil nutrient application — an EASA-framework approval that creates a replicable template for expansion across Europe. That's significant because it means the regulatory groundwork for continent-wide agricultural drone services is already being laid — and in a market where early authorization can translate directly into competitive advantage. Its new IQ Octo drone has completed its initial prototype and entered testing, purpose-built for autonomous precision spraying and seeding in a sector that market analysts project could grow at more than 30% annually. Precision agriculture is one of those verticals where drone-based automation can offer a measurable return on every acre — reduced chemical usage, faster coverage, and data-driven application maps that improve yield outcomes over time. The company is also developing a franchise model for drone-based power washing — a market valued at over $5B globally in 2024 and projected to reach over $15B by 2031, per Valuates Reports. A franchise approach could allow (ZENA) to scale its commercial DaaS footprint without bearing the full capital burden of each new territory — essentially turning its operator network into a distribution channel. And then there's the enterprise software arm — a quieter part of the story, but one worth understanding. Zoo Office™ is an AI-powered productivity platform that consolidates 13 existing software brands into a unified suite for business and government customers. That consolidation move is worth watching on its own — merging 13 brands into a single platform creates cross-sell potential across the entire DaaS customer base, and it adds a software-as-a-service layer to what is already a services-driven revenue model. When you look across all of these verticals — surveying, defense, agriculture, power washing, enterprise software — the common thread is a platform designed to absorb new services and scale them through technology. That's the kind of architecture that tends to compound… 7 Reasons Why We Have (ZENA) Pulled Up On Our Screen This Morning—Wednesday, October 7, 2026…
1. 316% Q2 Revenue Growth: Second-quarter revenue reached $9.3M (CAD), a 316% year-over-year increase — the seventh consecutive quarter of sequential growth — with quarterly figures expanding more than 13x since Q4 2024, per the shareholder letter. 2. 29 DaaS Acquisitions Spanning 14 States: The roll-up strategy has now completed 29 acquisitions across surveying, inspection, and service verticals, with signed offers expected to contribute approximately C$40M in first-year revenue upon closing. 3. ZenaDrone 2000 Heavy-Lift Interceptor Advancing: The gasoline-powered counter-UAS platform, designed for 4+ hours of hover endurance, is moving through prototype assembly with flight testing expected Q1 2027. 4. Canada Defence Drone Initiative Selection: ZenaTech has been selected as a qualified supplier under Canada's DDI Marketplace, creating a pathway to future Canadian Armed Forces and Coast Guard drone requirements. 5. Quantum Navigation Enters Drone Testing: ZenaDrone's defense-focused quantum navigation system has advanced to the testing phase, designed for secure operations in GPS-denied environments — a mission-critical capability for modern defense applications. 6. Russell 3000® Index Inclusion: Added to the Russell 3000 in June 2026, an important recognition milestone that could broaden institutional visibility. 7. Analyst Coverage: Maxim Group maintains a bullish rating with a $5 target — compared to a recent range near $1.30. Pull Up (ZENA) While It’s Still Early…
When you step back and look at the full picture — triple-digit revenue growth, 29 acquisitions and counting, defense drone systems advancing toward flight testing, government qualifications from an allied nation, a Russell 3000 listing, and a balance sheet with $34.6M in cash and securities — it's hard not to see something substantial taking shape here… The DaaS roll-up is delivering real revenue now. The defense pipeline is advancing toward real flight tests. The commercial verticals are expanding into real new markets with real regulatory authorizations in hand. And the enterprise software consolidation adds yet another dimension to a story that already has more moving parts than most companies at this stage. We have (ZENA) pulled up early this morning. Take a look at it while it’s still early and watch for our next update. Sincerely, Gary Silver
Managing Editor,
Market Crux |


0 التعليقات:
إرسال تعليق